


[Jan-2022] 2016-FRR Certification with Actual Questions from TestInsides
Updated 2016-FRR Dumps PDF - 2016-FRR Real Valid Brain Dumps With 345 Questions!
NEW QUESTION 41
An endowment asset manager with a focus on long/short equity strategies is evaluating the risks of an equity
portfolio. Which of the following risk types does the asset manager need to consider when evaluating her
diversified equity portfolio?
I. Company-specific projected earnings and earnings risk
II. Aggregate earnings expectations
III. Market liquidity
IV. Individual asset volatility
- A. II, III
- B. I
- C. I, IV
- D. I, II, IV
Answer: A
NEW QUESTION 42
A risk manager has a long forward position of USD 1 million but the option portfolio decreases JPY 0.50 for
every JPY 1 increase in his forward position. At first approximation, what is the overall result of the options
positions?
- A. The option positions hedge the forward position by 75%.
- B. The options positions hedge the forward position by 25%.
- C. The option positions hedge the forward position by 100%.
- D. The option positions hedge the forward position by 50%.
Answer: D
NEW QUESTION 43
A customer of EtaBank, Alfred Fall, fell on the marble floors of the bank and sustained substantial injuries.
Subsequently, he won a personal injury claim of $50,000 against EtaBank. How should EtaBank's operational
loss data event information database categorize this event?
- A. This event would not qualify as an operational risk event.
- B. This event would qualify as "Legal Risk".
- C. This event would qualify as "Employment Practices and Workplace Safety".
- D. This event would qualify as "Business Disruption and System Failures".
Answer: C
NEW QUESTION 44
Which of the following are among the main uses of risk reports?
I. Identification of exceptional situations that require managerial attention.
II. Display the relative risk among different trades.
III. Specify how RAROC will be maximized within the bank.
IV. Estimate the overall risk levels of the bank.
- A. I, II and IV
- B. II and III
- C. II and IV
- D. II, III, and IV
Answer: A
NEW QUESTION 45
Which one of the four following statements about back testing the VaR models is correct?
Back testing requires
- A. Comparing the predictive ability of VaR on a daily basis to the realized daily profits and losses.
- B. Plotting the daily profit and losses along with the ranges predicted by VaR models
- C. Plotting VaR forecasts against the proportion of daily losses exceeding the average loss.
- D. Determining the proportion of daily profits exceeding those predicted by VaR.
Answer: A
NEW QUESTION 46
Which of the following statements about endogenous and exogenous types of liquidity are accurate?
I. Endogenous liquidity is the liquidity inherent in the bank's assets themselves.
II. Exogenous liquidity is the liquidity provided by the bank's liquidity structure to fund its assets and maturing
liabilities.
III. Exogenous liquidity is the non-contractual and contingent capital supplied by investors to support the bank
in times of liquidity stress.
IV. Endogenous liquidity is the same as funding liquidity.
- A. I, III
- B. I, II, IV
- C. I, II
- D. II, III
Answer: C
NEW QUESTION 47
Changes to which one of the following four factors would typically not increase the cost of credit?
- A. Higher risk premium on a fixed income instrument.
- B. Increase in consumption of goods and services.
- C. Higher return earned on alternative investments.
- D. Increasing inflation rates in a country.
Answer: A
NEW QUESTION 48
A corporate bond gives a yield of 6%. A same maturity government bond yields 2%. The probability of the
corporate bond defaulting is 2.5%. In case of default, investors expect to lose 60% of their investment. The
risk premium in the credit spread is:
- A. 1.5%
- B. 4.5%
- C. 2.5%
- D. 0.5%
Answer: C
NEW QUESTION 49
Which of the following statements are reasons for mathematical valuation and risk assessment models to be
misleading or inaccurate?
I. There could be missing factors in models.
II. The data used as input for the model could be bad or wrong.
III. Model results could be misinterpreted.
IV. There could be errors in the derivation of the model.
- A. I, II, III IV
- B. I, III, and IV
- C. III and IV
- D. I, II, and III
Answer: A
NEW QUESTION 50
As DeltaBank explores the securitization business, it is most likely to embrace securitization to:
I. Bring transparency to the bank's balance sheet
II. Create a new profit center for the bank
III. Strategically release risk capital and regulatory capital for redeployment
IV. Generate cash for additional debt origination
- A. II, IV
- B. I, II, III
- C. I, III
- D. II, III, IV
Answer: D
NEW QUESTION 51
DeltaFin wants to develop a control scoring method for its RCSA program. Which of the following statements
regarding scoring methods are correct?
I. DeltaFin can develop a control scoring method that assesses both the design and the performance of the
control.
II. DeltaFin can combine the design and performance scores for each control to produce an overall control
effectiveness score.
III. DeltaFin can use the control performance scores to compute an overall risk severity score.
IV. DeltaFin can determine its own appropriate control scoring method.
- A. I, II and IV
- B. II and III
- C. I only
- D. II, III, and IV
Answer: A
NEW QUESTION 52
Which one of the following four statements about the relationship between exchange rates and option values is
correct?
- A. As the dollar appreciates relative to the pound, the right to sell dollars at a fixed pound exchange rate
increases. - B. As the dollar appreciates relative to the pound, the right to buy dollars at a fixed pound exchange rate
increases. - C. As the dollar appreciates relative to the pound, the right to buy dollars at a fixed pound exchange rate
decreases. - D. As the dollar depreciates relative to the pound, the right to buy dollars at a fixed pound exchange rate
increases.
Answer: B
NEW QUESTION 53
Gamma Bank has a significant number of retail customers and finds its balance sheet shape and structure
difficult to manage. Which one of the following characteristics of a bank with wide retail operations is
INCORRECT?
- A. Attracting and retaining customers often involves offering retail products whose features are different
from wholesale market products. - B. Banks with a wide retail base are typically driven by contractual obligations and not simply relationship
considerations. - C. The way retail customers behave in relation to the retail banking products they hold often results in the
apparent contractual obligation of the parties providing a poor description of the actual nature of the
obligations. - D. Pricing of retail products often has more to do with marketing considerations rather than prevailing
market price.
Answer: B
NEW QUESTION 54
A bank customer expecting to pay its Brazilian supplier BRL 100 million asks Alpha Bank to buy Australian
dollars and sell Brazilian reals. Alpha bank does not hold Brazilian reals so it asks for a quote to buy Brazilian
reals in the market. The market rate is 100. The bank quotes a selling rate of 101 to its customer, sells the
reals, and receives AUD 1,010,000. To perform foreign exchange matched position trading, the banks should
- A. Immediately buy the real at the market rate of 100 and pay AUD 1,000,000.
- B. Immediately buy the real above the market rate of 105 and pay AUD 1,050,050.
- C. Immediately sell the real at the market rate of 100 and receive AUD 1,000,000.
- D. Immediately sell the real above the market rate of 105 and receive AUD 1,050,050.
Answer: A
NEW QUESTION 55
Mega Bank has $100 million in deposits on which it pays 3% interest, and $20 million in equity on which it
pays no interest. The loan portfolio of $120 million earns an average rate of 10%. If the rates remain the same,
what is the net interest income of Mega Bank?
- A. $12 million per year
- B. $2 million per year
- C. $5 million per year
- D. $9 million per year
Answer: D
NEW QUESTION 56
A portfolio consists of two floating rate bonds and one fixed rate bond.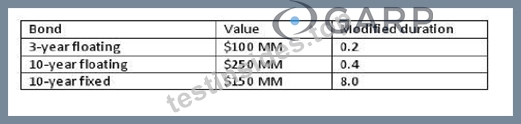
Based on the information below, modified duration of this portfolio is
- A. 4.44
- B. 2.64
- C. 3.00
- D. 4.28
Answer: B
NEW QUESTION 57
For a bank a 1-year VaR of USD 10 million at 95% confidence level means that:
- A. There is a 5% chance that the worst loss would be USD 10 million in a year.
- B. There is a 5% chance that the bank would lose less than USD 10 million in a year.
- C. There is a 5% chance that the least loss would be USD 10 million in a year.
- D. There is a 5% chance that the bank would lose more than USD 10 million in a year.
Answer: D
NEW QUESTION 58
Which of the following would a bank resort to as a "lender of last resort" in the event of an extreme liquidity
crisis?
- A. Futures Markets
- B. U.S treasury markets
- C. LIBOR markets
- D. Discount window
Answer: D
NEW QUESTION 59
To estimate the price of gold forwards, an investment analyst focuses on the cost of holding physical gold
(bullion) and the cost of shorting the same. Given that physical gold spot price is $1,000, the annual risk-free
rate is 5%, and the gold lease rate equals 2% annually, the analyst's best estimate of the gold forward price to
equal
- A. $1070
- B. $1030
- C. $1100
- D. $950
Answer: B
NEW QUESTION 60
......
Pass Your 2016-FRR Exam Easily With 100% Exam Passing Guarantee: https://www.testinsides.top/2016-FRR-dumps-review.html
100% Free 2016-FRR Exam Dumps Use Real Financial Risk and Regulation Dumps: https://drive.google.com/open?id=1keEaZ-f0TH1pzCL2_5rqzClLR4nyaadt